
IRA Calculator: Estimate your retirement savings growth 💰
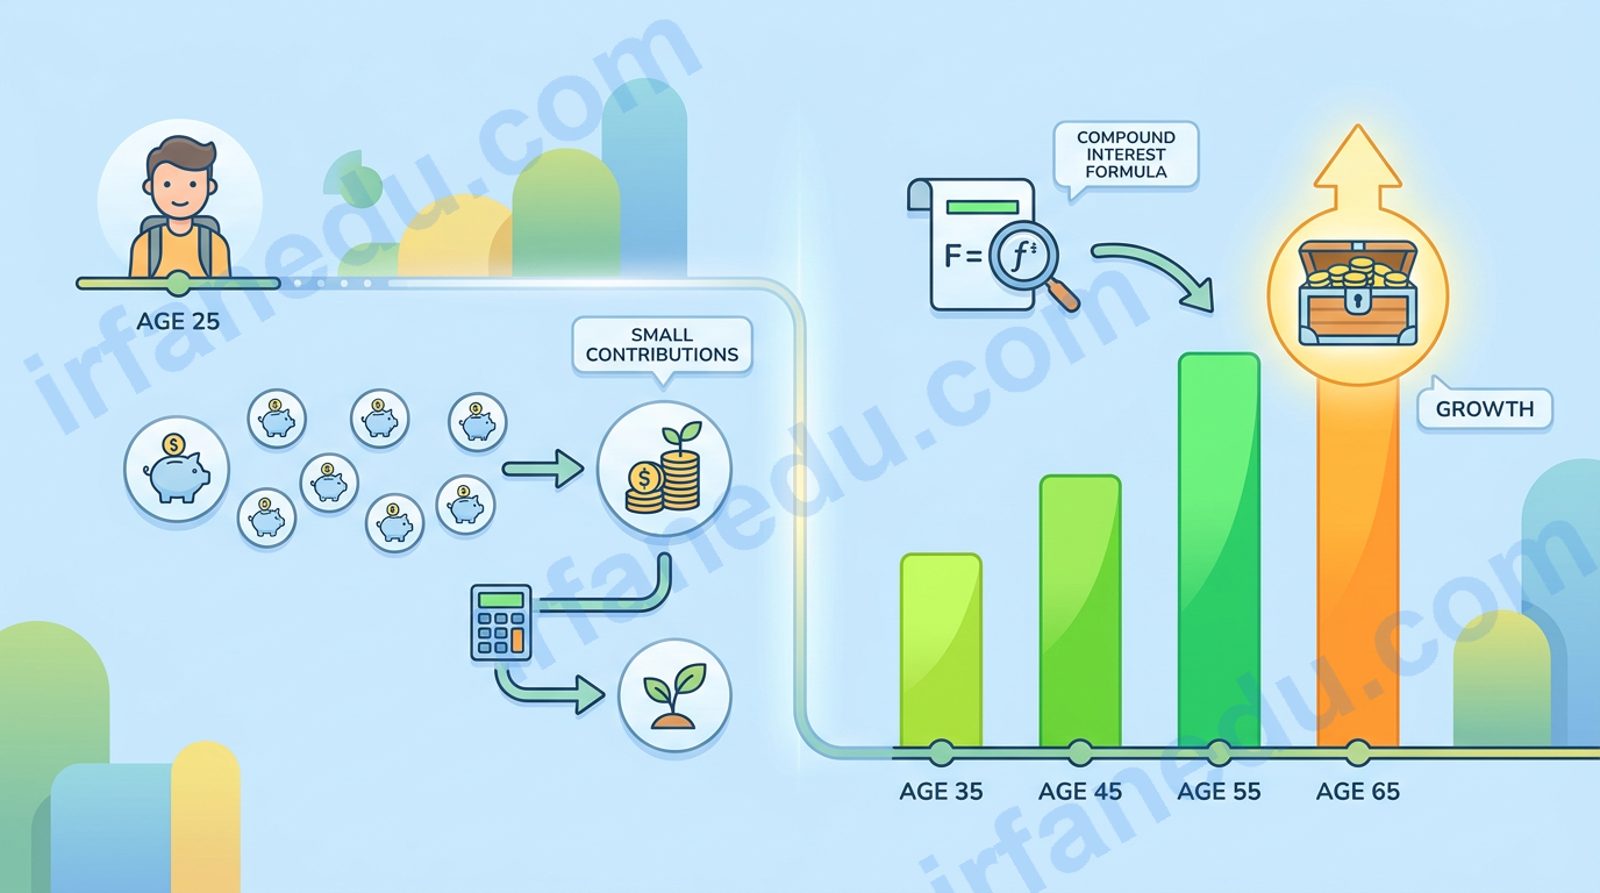
Think of your IRA like a snowball rolling down a long hill. 🏔️ A small snowball pushed early gathers more snow with every rotation — and by the time it reaches the bottom, it is enormous. Your retirement account works exactly the same way: the earlier you start, the more compound interest does the heavy lifting for you.
This free IRA calculator lets you punch in four numbers and instantly see your projected retirement balance, the math behind it, and a step-by-step breakdown. No spreadsheet needed.
An IRA calculator estimates your Individual Retirement Account balance at retirement. Enter your current balance, annual contribution, expected annual return rate, and years to retirement. The formula is: FV = PV × (1+r)^n + PMT × [(1+r)^n − 1] / r. A 25-year-old contributing $6,500/year at 7% for 40 years can accumulate roughly $1.37 million — most of it pure compound interest.
⚡ In Short
- 🧮 Uses compound interest formula to project IRA balance at retirement.
- 📅 Starting earlier dramatically increases final value — time beats contribution size.
- 💡 7% is the standard historical real-return estimate for a diversified index portfolio.
- 🏦 Traditional IRA = tax deduction now; Roth IRA = tax-free withdrawals later.
- 📈 2024–2025 contribution limit: $7,000/year ($8,000 if age 50+).
How to use this IRA calculator 🛠️
The calculator has two modes. Switch between them using the orange buttons at the top of the widget.
- Future Value mode: Enter your current IRA balance (use 0 if you are starting fresh), your planned annual contribution, your expected annual return rate, and the number of years until you retire. Hit Calculate.
- Required Contribution mode: Enter your retirement savings goal, current balance, expected return, and years. The calculator tells you exactly how much you need to save each year — and breaks it down monthly.
- Read the step-by-step solution in the green result card to see exactly how the number was computed.
- Adjust any input and recalculate to run "what if" scenarios instantly.
What is an IRA? 🏦
An Individual Retirement Account (IRA) is a tax-advantaged savings account that lets you invest money for retirement with special tax benefits. It is not an investment itself — it is a legal wrapper around investments like index funds, stocks, or bonds.
Think of it like a special lunchbox 🍱. The lunchbox does not make the food, but it keeps everything fresh and protected. The IRA does not generate returns on its own — it protects your investments from taxes while they grow.
In my experience explaining retirement accounts to students and young professionals, the biggest misconception I encounter is thinking an IRA is an investment. It is not. It is a tax shelter. The actual returns come from what you put inside it. Once that clicks, the whole system makes sense.
| Fact | Detail |
|---|---|
| Full name | Individual Retirement Account |
| 2024–2025 contribution limit | $7,000/year ($8,000 if age 50+) |
| Main types | Traditional IRA, Roth IRA, SEP IRA, SIMPLE IRA |
| Tax treatment (Traditional) | Contributions may be tax-deductible; withdrawals taxed |
| Tax treatment (Roth) | Contributions after-tax; qualified withdrawals tax-free |
| Required minimum distributions | Traditional: starts at age 73; Roth: none during owner's lifetime |
| Early withdrawal penalty | 10% penalty if withdrawn before age 59½ (with exceptions) |
The IRA growth formula explained 📐
The calculator uses the standard compound interest future value formula for an annuity with an initial lump sum. This is the same formula used by financial planners worldwide.
FV = PV × (1 + r)^n + PMT × [(1 + r)^n − 1] / r
Where r > 0. When r = 0: FV = PV + PMT × n
| Symbol | Meaning | Unit / Notes |
|---|---|---|
| FV | Future Value — projected IRA balance | USD |
| PV | Present Value — current IRA balance | USD |
| PMT | Payment — annual contribution | USD/year |
| r | Annual return rate (decimal) | e.g. 7% → 0.07 |
| n | Number of years | Whole number, 1–60 |
The formula has two parts. The first term, PV × (1+r)^n, is the snowball effect on your existing balance — it grows exponentially. The second term, PMT × [(1+r)^n − 1] / r, is the future value of all your regular annual contributions, each one compounding for a different number of years. Together they give you the total projected balance.
Worked examples 🔢
Example 1 — Starting at 25 with a small balance
- Inputs: PV = $2,000, PMT = $6,500/yr, r = 7% (0.07), n = 40 years.
- Growth factor: (1.07)^40 = 14.9745.
- FV of current balance: $2,000 × 14.9745 = $29,949.
- FV of contributions: $6,500 × (14.9745 − 1) / 0.07 = $6,500 × 199.635 = $1,297,628.
- Total FV = $29,949 + $1,297,628 = $1,327,577.
- Total contributed: $2,000 + ($6,500 × 40) = $262,000. Interest earned: $1,065,577 — that is over 4× the money you put in.
Example 2 — Starting at 35, same contributions
- Inputs: PV = $0, PMT = $6,500/yr, r = 7%, n = 30 years.
- Growth factor: (1.07)^30 = 7.6123.
- FV of contributions: $6,500 × (7.6123 − 1) / 0.07 = $6,500 × 94.461 = $614,000.
- Waiting just 10 extra years cost this investor roughly $713,000 in final balance — despite contributing the same amount each year.
  Starting at 25 (n=40)          Starting at 35 (n=30)
  ─────────────────────          ─────────────────────
  Age 25  ████ $2,000            Age 35  ░ $0
  Age 35  ████████ $38K          Age 45  ████ $90K
  Age 45  ████████████ $148K     Age 55  ████████ $270K
  Age 55  ████████████████ $430K Age 65  ████████████ $614K
  Age 65  ████████████████████████████ $1,327K

  ★ 10 extra years of compounding = +$713K
Common mistakes people make with IRA calculations ⚠️
Most online IRA calculators give you a number but not the story behind it. Here are the errors I see most often — and how to fix them.
| ❌ Mistake | ✅ Correct approach |
|---|---|
| Using 10% return (nominal S&P 500 average) | Use 7% — the approximate real (inflation-adjusted) return for a diversified index portfolio |
| Forgetting to account for contribution limits | Cap annual PMT at $7,000 ($8,000 if 50+) unless using a SEP or SIMPLE IRA |
| Treating the IRA balance as spendable at face value | Traditional IRA withdrawals are taxed as ordinary income — budget for that |
Assuming
Sources & ReferencesWritten and fact-checked by Dr Irfan Mansuri. External links open in a new tab and are provided for further reading and verification. |