
Credit card payoff calculator: clear your debt faster
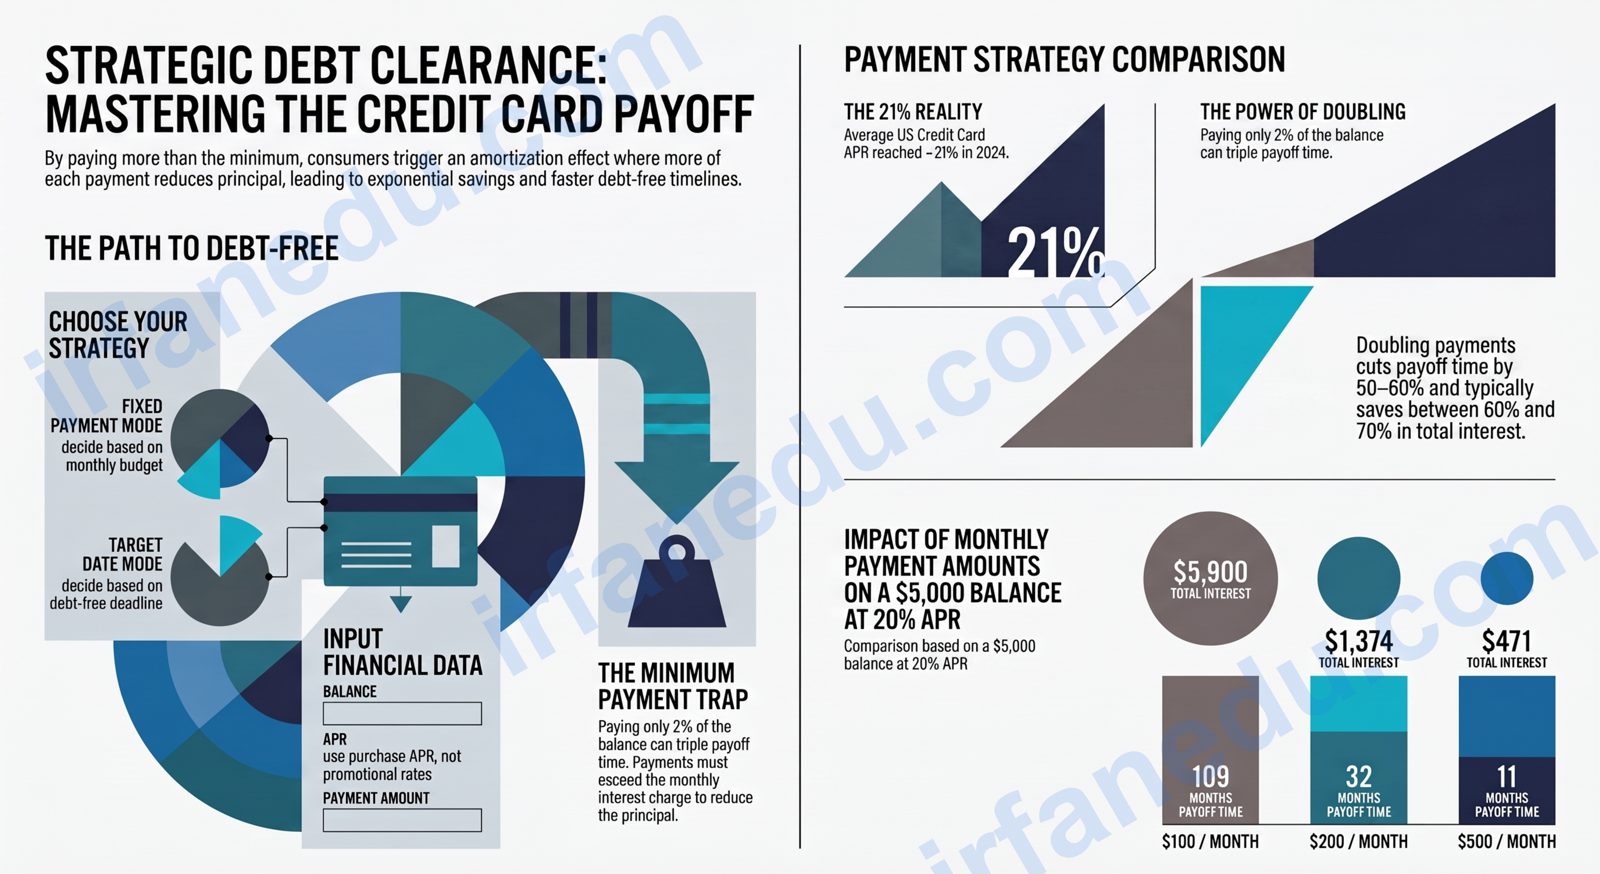
| Quick fact | Detail |
|---|---|
| Formula used | Standard loan amortization (monthly compounding) |
| Inputs needed | Balance, APR (%), monthly payment or target months |
| Average US credit card APR (2024) | ~21% (CFPB data) |
| Minimum payment trap | Paying only 2% of balance on $5,000 at 20% APR takes ~94 months and costs ~$2,600 in interest |
| Doubling your payment | Typically cuts payoff time by 50–60% and saves 60–70% of interest |
| Calculator modes | Fixed payment → months; Target months → required payment |
This free credit card payoff calculator tells you exactly how long it will take to clear your balance — and how much interest you will pay — based on your APR and monthly payment. Switch to the second mode to find the payment you need to be debt-free by a specific deadline. The math runs entirely in your browser; no data is sent anywhere.
- Enter balance, APR, and monthly payment to see your exact payoff date.
- Mode 2 calculates the payment you need to hit a target payoff month.
- The formula is standard amortization — the same math banks use.
- Paying even $50 extra per month can save hundreds in interest.
- Your payment must exceed monthly interest or the balance never falls.
Credit Card Payoff Calculator
Free · Instant · No sign-up
%
Must be greater than monthly interest charge to reduce the balance.
%
months
How to use this calculator
Using the tool takes under a minute. Follow these steps:
- Choose a mode. Select “Fixed payment → months” if you know what you can afford each month. Select “Target months → payment needed” if you have a debt-free deadline in mind.
- Enter your current balance. Check your latest statement for the exact figure.
- Enter your APR. This is on your statement or card agreement — use the purchase APR, not a promotional rate.
- Enter your monthly payment or target months depending on the mode.
- Click Calculate. The result card shows your payoff time (or required payment), total interest, and a numbered solution you can follow manually.
What is credit card interest and how is it calculated?
Credit card interest is the cost of carrying an unpaid balance from one billing cycle to the next. Each month, your card issuer multiplies your outstanding balance by the monthly periodic rate (APR divided by 12) to produce an interest charge, which is added to your balance before your payment is applied.
The key formula for a single month is:
Interest this month = Balance × (APR / 12)
Because the balance falls each month as you pay it down, the interest charge also falls — this is the amortization effect. Early payments are mostly interest; later payments are mostly principal.
The payoff formula explained
The calculator uses the standard loan amortization formula, solved for the number of periods:
n = −log(1 − r·B / P) / log(1 + r)P = B·r·(1+r)^n / ((1+r)^n − 1)
| Symbol | Meaning | Unit / notes |
|---|---|---|
| B | Current balance (principal) | Dollars ($) |
| APR | Annual percentage rate | % per year |
| r | Monthly periodic rate = APR / 12 | Decimal (e.g. 0.20/12 ≈ 0.01667) |
| P | Fixed monthly payment | Dollars ($); must exceed B·r |
| n | Number of months to payoff | Integer months (rounded up) |
| Total interest | Sum of all monthly interest charges | Dollars ($) |
SI / units note: All monetary values are in the same currency (USD by default). Time is in months. The formula assumes end-of-period payments and monthly compounding — the standard for US credit cards.
Worked examples that match the calculator’s output
Inputs: Balance = $3,000 | APR = 18% | Monthly payment = $100
- Monthly rate r = 18% / 12 = 1.5% = 0.015
- Month 1 interest = $3,000 × 0.015 = $45.00
- Month 1 principal = $100 − $45 = $55 → new balance $2,945
- n = −log(1 − 0.015 × 3000 / 100) / log(1.015) = −log(0.55) / log(1.015) ≈ 38 months
- Total interest ≈ $762 | Total paid ≈ $3,762
Inputs: Balance = $5,000 | APR = 20% | Target = 24 months
- Monthly rate r = 20% / 12 ≈ 0.016667
- P = 5000 × 0.016667 × (1.016667)^24 / ((1.016667)^24 − 1)
- (1.016667)^24 ≈ 1.4859
- P = 5000 × 0.016667 × 1.4859 / (1.4859 − 1) = 123.83 / 0.4859 ≈ $254.79/month
- Total paid ≈ $6,115 | Total interest ≈ $1,115
Inputs: Balance = $5,000 | APR = 20% | Monthly payment = $100 (near-minimum)
- Monthly rate r ≈ 0.016667
- Month 1 interest = $5,000 × 0.016667 = $83.33 — payment barely covers interest
- n = −log(1 − 0.016667 × 5000 / 100) / log(1.016667) = −log(0.1667) / log(1.016667) ≈ 109 months (over 9 years)
- Total interest ≈ $5,900 — you pay more in interest than the original balance
  $5,000 balance | 20% APR — Payment strategy comparison
  ─────────────────────────────────────────────────────
  Payment    │ Months │ Total interest │ Total paid
  ───────────┼────────┼────────────────┼────────────
  $100/mo    │  109   │   ~$5,900      │  ~$10,900
  $150/mo    │   49   │   ~$2,306      │   ~$7,306
  $200/mo    │   32   │   ~$1,374      │   ~$6,374
  $300/mo    │   20   │     ~$784      │   ~$5,784
  $500/mo    │   11   │     ~$471      │   ~$5,471
  ─────────────────────────────────────────────────────
  Each row uses the amortization formula n = -log(1-rB/P)/log(1+r)
Minimum payment vs. fixed payment: a direct comparison
Most card issuers set a minimum payment of about 1–2% of the outstanding balance (or $25, whichever is greater). Because the minimum shrinks as the balance falls, you end up paying a declining amount each month — and the payoff drags on for years.
| Strategy | Monthly payment | Payoff time
Sources & ReferencesWritten and fact-checked by Dr Irfan Mansuri. External links open in a new tab and are provided for further reading and verification. |
|---|