
Whole Life Insurance Calculator (With Worked Examples)
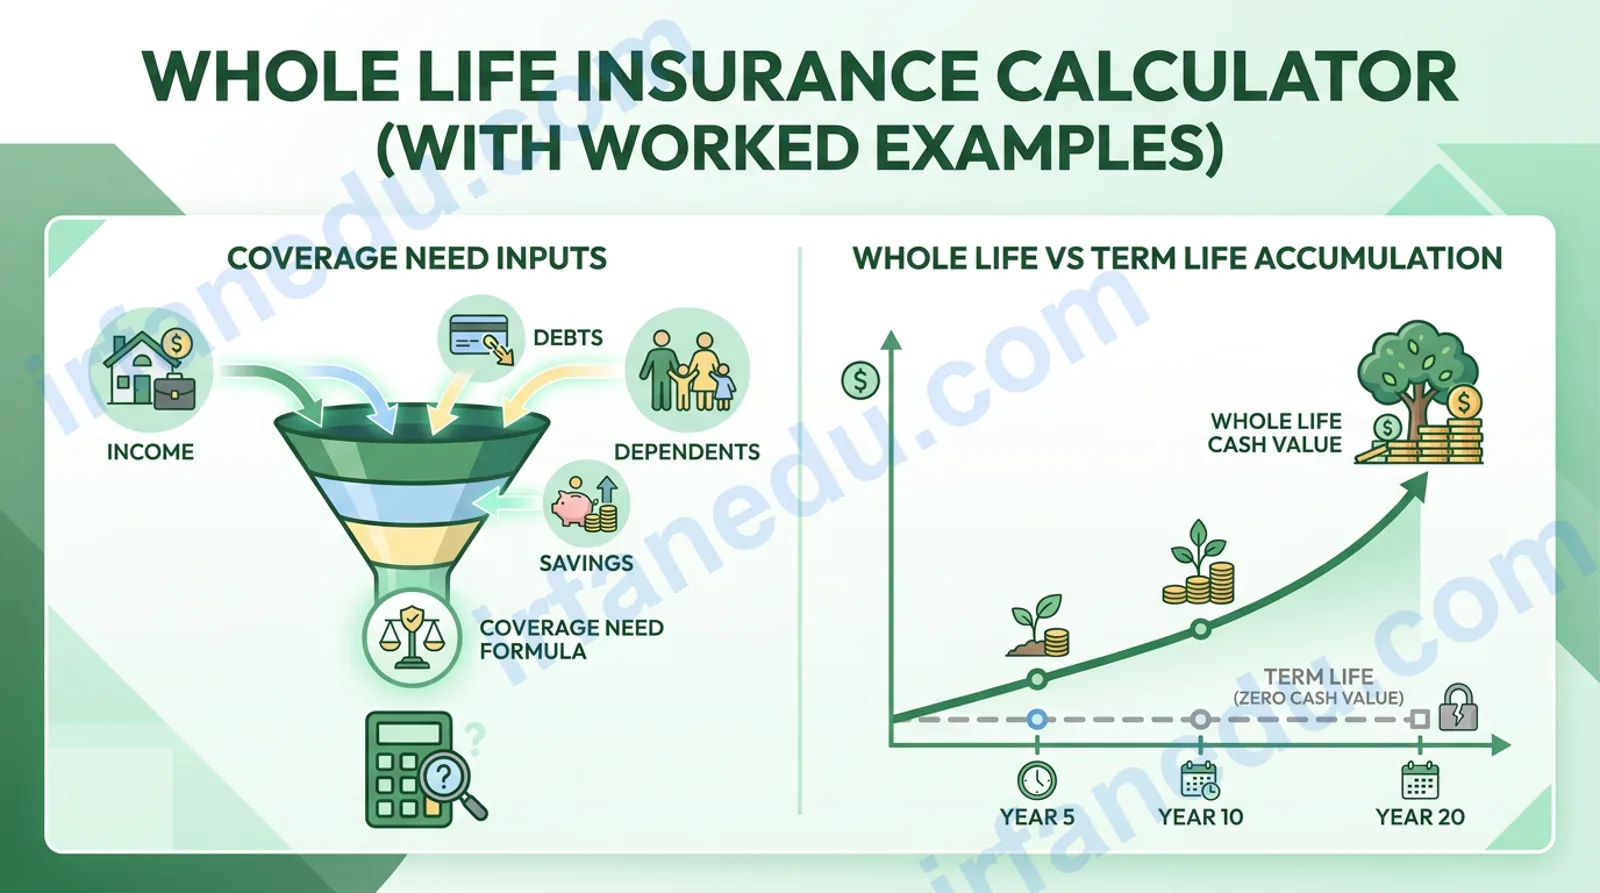
Choosing a whole life insurance policy without numbers in front of you is like buying a house without knowing the asking price. You need three figures before you talk to any agent: how much coverage you actually need, what the monthly premium will run, and how your policy’s cash value builds over time. This calculator gives you all three — instantly, with full step-by-step math — so you walk into that conversation informed.
A whole life insurance calculator is a tool that estimates your ideal death benefit, projected monthly premium, and long-term cash value accumulation based on your income, debts, dependents, age, and health class. It uses the DIME method for coverage sizing and published US carrier rate averages for premium estimation.
A whole life insurance calculator estimates three things: (1) how much death benefit you need based on income, debts, and dependents; (2) what your monthly premium will cost; and (3) how your policy’s cash value grows over time. For a healthy 35-year-old non-smoker in the US, a $500,000 whole life policy typically costs $300–$500 per month — roughly 5–15× more than equivalent term life coverage.
🎯 The Short Version
- 🧮 Coverage need = (10–12× income) + debts − savings — the DIME method refines this.
- 💵 Premiums are fixed for life — your rate locks in at the age you buy.
- 📈 Cash value grows tax-deferred at a guaranteed rate (typically 2–4% annually).
- ⚖️ Whole life costs 5–15× more than term life for the same death benefit.
- 🏦 Best for: lifelong coverage needs, estate planning, or special-needs dependents.
- 🔢 Use this calculator as a benchmark — always get formal illustrations from a licensed agent.
Whole Life Insurance Calculator
USD / yr
USD
USD
years
How to Use This Whole Life Insurance Calculator
The calculator has three modes. Pick the one that matches your question right now.
- Coverage Need — Enter your annual income, total debts, existing savings, and how many years of income your family would need. The calculator applies the DIME method to output a recommended death benefit.
- Monthly Premium — Enter your age, desired coverage amount, and health class. The calculator uses averaged rate tables from major US carriers to estimate your monthly cost.
- Cash Value Projection — Enter your monthly premium, policy duration, and the guaranteed growth rate from your illustration. The calculator projects how much tax-deferred cash value your policy builds.
Use the result as a benchmark. Always request a formal illustration from a licensed insurance agent before buying.
What Is Whole Life Insurance?
Whole life insurance is a type of permanent life insurance that provides a guaranteed death benefit for your entire life, as long as you pay premiums. Unlike term life, it never expires and includes a cash value component that grows at a guaranteed minimum rate.
Every premium payment splits three ways: a portion covers the cost of insurance (mortality charge), a portion covers the insurer’s expenses, and the remainder builds your policy’s cash value. Over decades, that cash value can become substantial — and you can borrow against it tax-free or surrender the policy for its accumulated value.
The Formulas This Calculator Uses
Coverage Need = (Annual Income × Years) + Total Debts − Existing Savings
Annual Premium = (Coverage ÷ 1,000) × Rate per $1,000
Monthly Premium = Annual Premium ÷ 12
Cash Value (FV) = Monthly CV Contribution × [((1 + r/12)^(n) − 1) / (r/12)]

where r = annual guaranteed rate, n = months, CV contribution ≈ 30% of monthly premium
| Symbol | Meaning | Unit |
|---|---|---|
| n | Number of months (policy duration) | months |
| r | Guaranteed annual growth rate (decimal) | decimal |
| CV | Cash value at end of projection period | USD |
| Rate/K | Annual premium per $1,000 of face amount | USD per $1,000 |
| FV | Future value of cash value contributions | USD |
Whole Life vs. Term Life: Which One Should You Use?
This is the question most people are actually asking when they search for a whole life insurance calculator. The right answer depends on your specific situation — not a blanket rule.
| Factor | Whole Life | Term Life |
|---|---|---|
| Coverage duration | Lifetime (permanent) | Fixed term (10–30 years) |
| Premium | Fixed, higher | Fixed during term, lower |
| Cash value | Yes — guaranteed growth | No |
| Death benefit | Guaranteed, never expires | Expires at end of term |
| Cost for $500K, age 35 | ~$300–$500/mo | ~$25–$40/mo |
| Best for | Estate planning, lifelong dependents, forced savings | Income replacement during working years |
| Flexibility | Low (fixed premium) | High (buy only what you need) |
According to the Insurance Information Institute — Types of Permanent Life Insurance, whole life is the most straightforward form of permanent coverage because every key variable is guaranteed at issue. That predictability is its main selling point.
Worked Examples That Mirror the Calculator
Example 1: Coverage Need
Sarah, 38, earns $90,000/year in Dallas, TX. She has a $250,000 mortgage, $30,000 in car loans, and $45,000 in savings. She wants to replace 10 years of income for her two children.
Income need  = $90,000 × 10 years  = $900,000
Add debts    = $900,000 + $280,000 = $1,180,000
Subtract savings = $1,180,000 − $45,000 = $1,135,000

Recommended coverage: $1,135,000
Example 2: Monthly Premium Estimate
Marcus, 42, is a non-smoker in Preferred health class. He wants $750,000 in whole life coverage.
- Rate for age 41–45, Preferred: $8.30 per $1,000
- Annual premium = (750,000 ÷ 1,000) × $8.30 = $6,225/year
- Monthly premium = $6,225 ÷ 12 = $518.75/month
Example 3: Cash Value Projection
Elena pays $400/month on her whole life policy. Her illustration shows a 3% guaranteed rate. After 20 years:
- Monthly CV contribution ≈ 30% × $400 = $120/month
- Monthly rate = 3% ÷ 12 = 0.25%
- n = 20 × 12 = 240 months
- Cash value = $120 × [((1.0025)^240 − 1) / 0.0025] ≈ $65,800
How Health Class Affects Your Whole Life Premium
Your health classification at underwriting is one of the biggest levers on your premium. Here is how the four main classes compare for a $500,000 policy at different ages.
| Age | Preferred Plus | Preferred | Standard | Tobacco |
|---|---|---|---|---|
| 30 | $133/mo | $150/mo | $183/mo | $333/mo |
| 35 | $171/mo | $192/mo
Sources & ReferencesWritten and fact-checked by Dr Irfan Mansuri. External links open in a new tab and are provided for further reading and verification. |